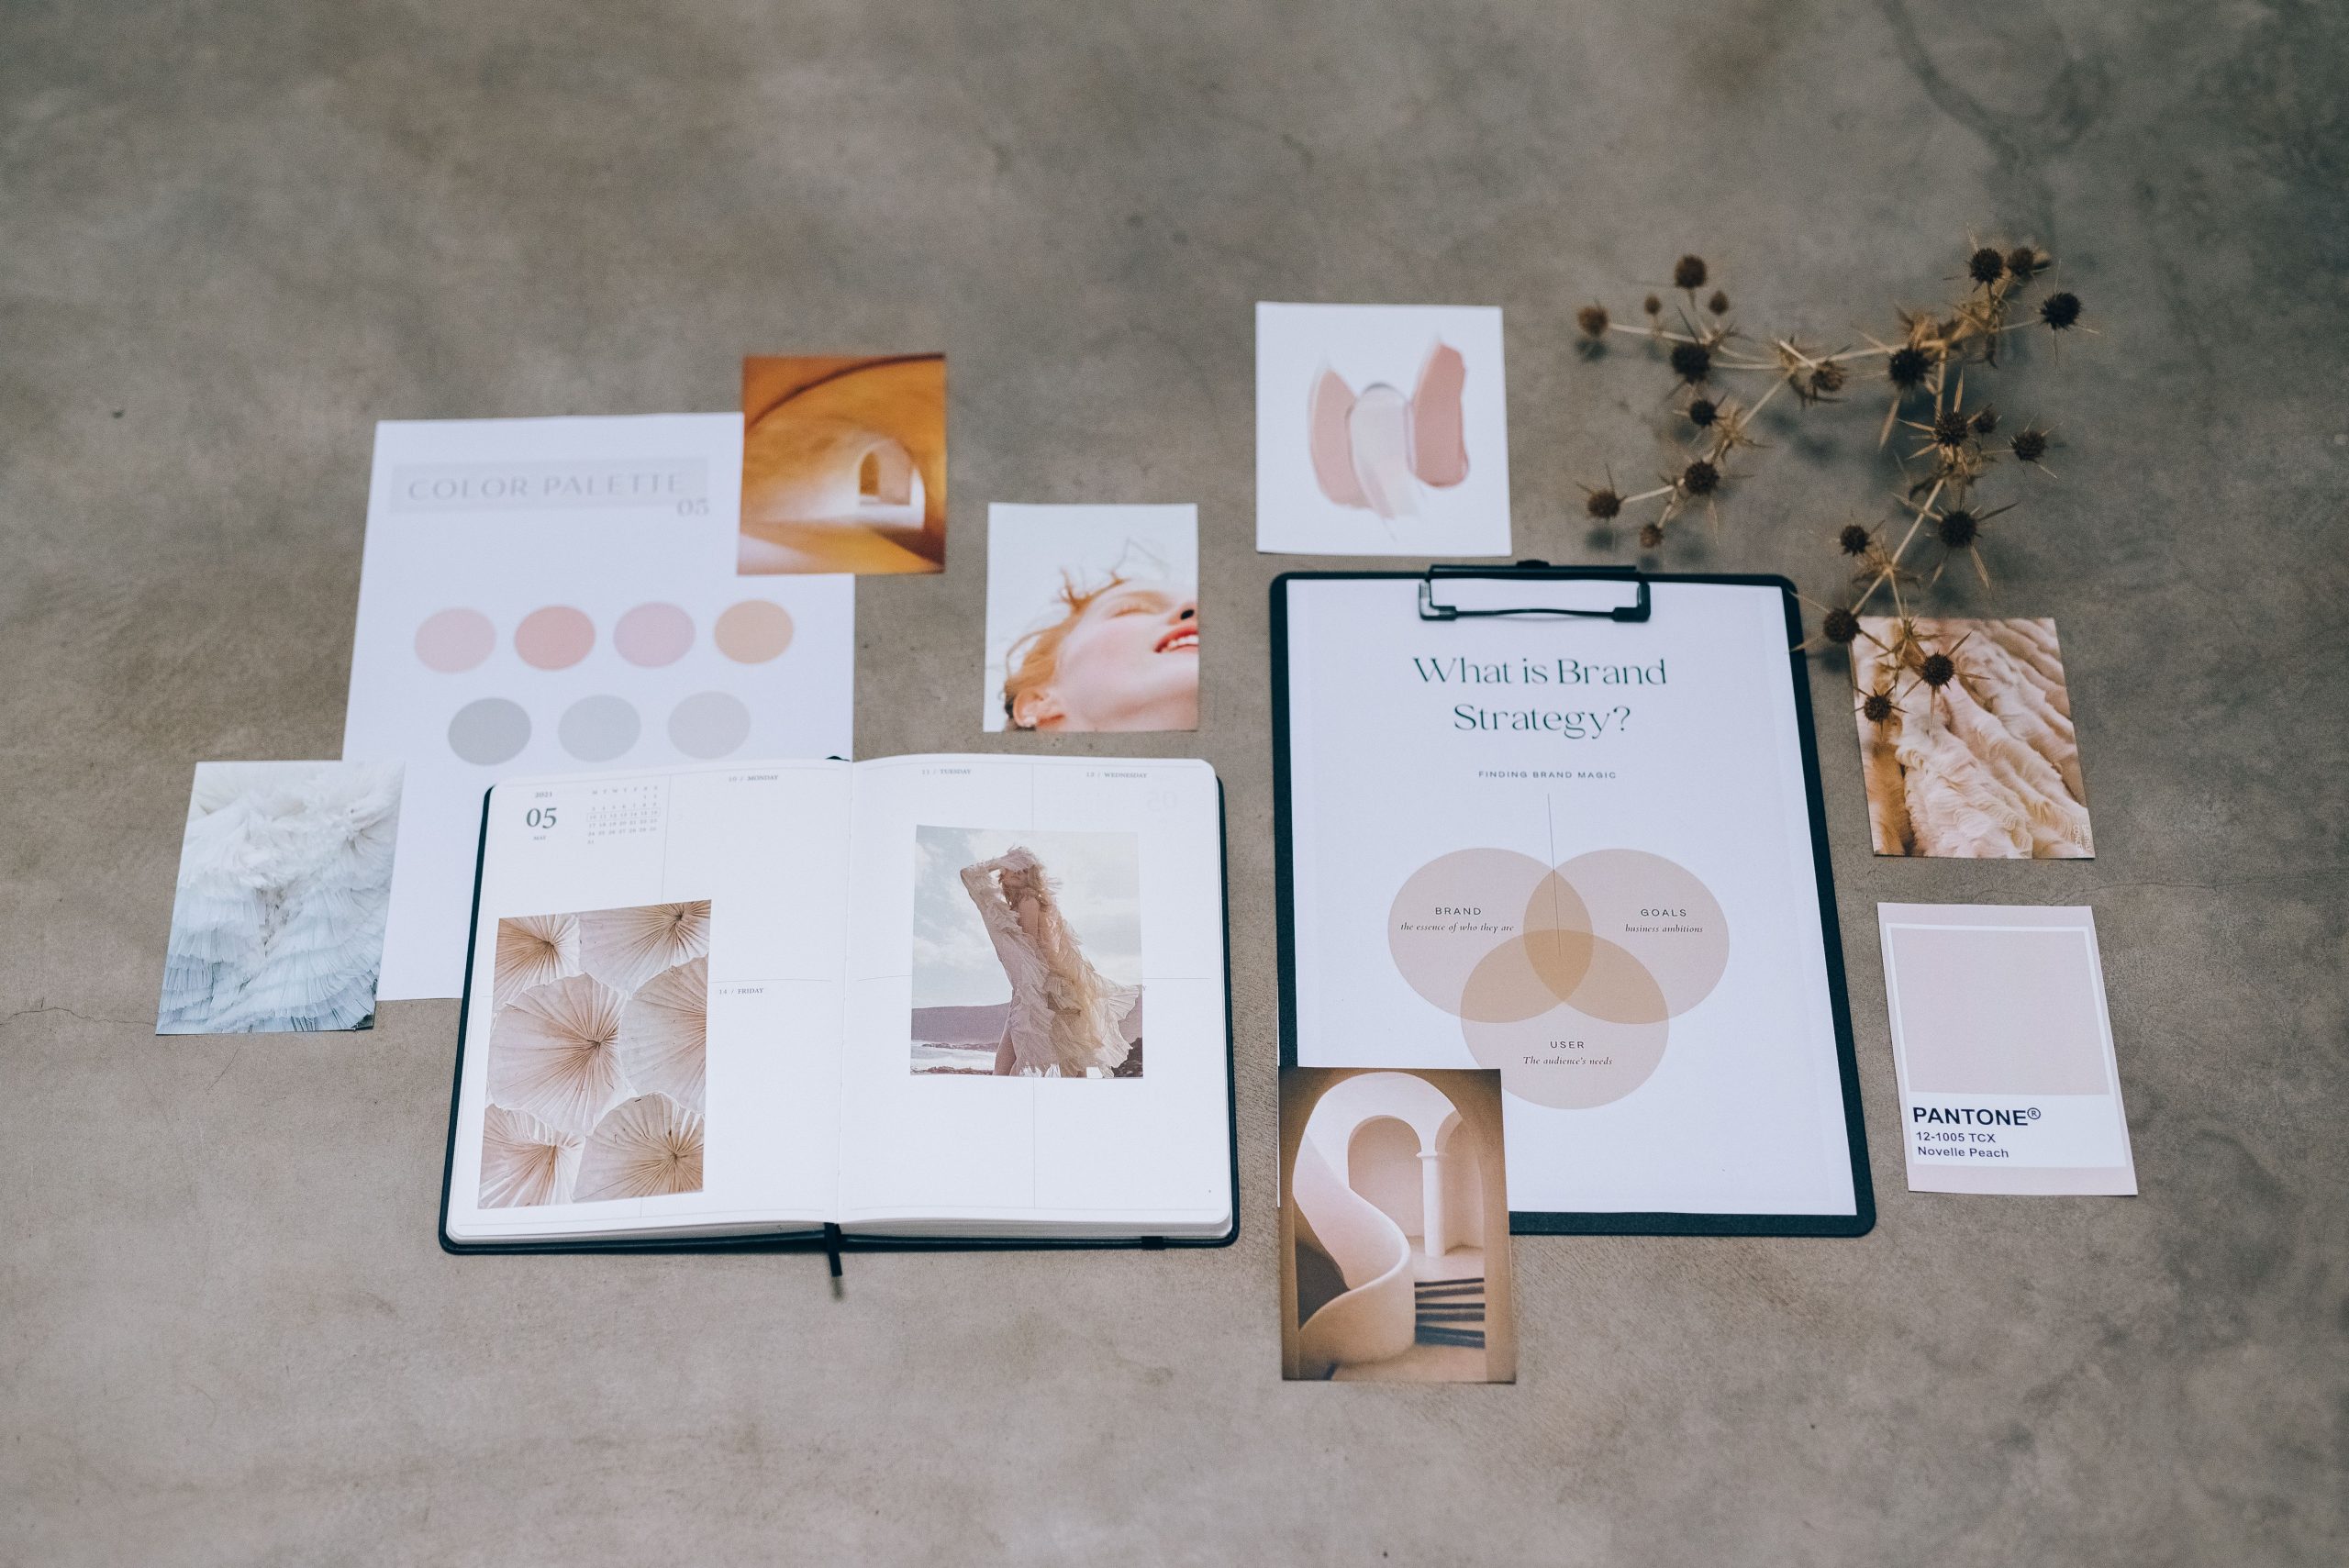
A rebrand is a deliberate change to a company’s name, logo, visual identity, messaging, or market positioning. Companies pursue rebrands for many reasons, from adapting to new markets to resolving problems with an older image. Because a rebrand touches marketing, operations, and finance at the same time, it is usually evaluated as a business decision rather than a purely creative one. This guide explains the main reasons companies rebrand, the financial considerations involved, and how the costs are generally treated in financial reporting.
Common Reasons Companies Decide to Rebrand
Rebrands are often grouped into external triggers, which come from the market, and internal triggers, which come from within the organization. Research on rebranding has identified both types as common drivers of these decisions.1 External triggers may include changing customer expectations, new competitors, or shifts in technology. Internal triggers often involve structural changes inside the business.
- Mergers and acquisitions: Two organizations may combine and need a single name and identity.
- Expansion into new markets or services: A brand name may no longer describe what the company offers.
- Outdated visual identity: Logos and design systems can start to look dated over time.
- Reputational repair: A new name or identity may be used to signal a fresh start, although this approach depends heavily on the circumstances.
- Digital readiness: Brands built for print or in-store use may need updated designs for websites, apps, and social platforms.
Professional services are one sector where these considerations come up frequently. Firms may review names, visual identities, and positioning as they grow or change ownership, which is part of the wider discussion around corporate rebranding in professional services.
How Rebranding Affects Brand Equity
Brand equity refers to the value a brand holds in the minds of customers and, in financial terms, in the business itself. Much of the academic literature treats brand equity as a central concern in rebranding decisions. A key point is that a rebrand can preserve or disrupt existing customer associations. Studies of brand equity have noted that changing a well-known name or symbol can affect the associations customers already hold, which is why many companies try to carry familiar elements into the new identity.
The table below summarizes common rebranding triggers and the financial considerations each one tends to raise. These are general patterns rather than rules, and the actual impact depends on the company, its sector, and its market.
Because a rebrand can change how customers recognize a company, many organizations test the new identity with existing customers before a full launch. Testing does not remove all uncertainty, but it can give management evidence to compare against the expected benefits.
Financial Costs of a Rebrand
The cost of a rebrand depends on the scale of the company, the number of locations and products affected, and how much of the existing identity must be replaced. Costs are often grouped into the following categories:
- Strategy and research: Market studies, naming research, and consultant fees.
- Design and creative work: Logo design, brand guidelines, and creative development.
- Legal and registration: Trademark searches and filings, plus any changes to registered company names.
- Physical updates: Signage, vehicles, uniforms, stationery, and packaging.
- Digital updates: Website, app, search listings, email systems, and social media profiles.
- Communication and launch: Advertising, press activity, and customer notifications.
- Internal change management: Staff training and updated internal documents.
Some of these costs are one-time, while others, such as ongoing advertising to explain the new identity, may continue for a period after launch. Management teams commonly compare the total outlay with expected gains in revenue, pricing power, customer acquisition, or operational efficiency.
How Rebranding Costs Are Treated in Financial Reporting
How rebranding costs appear in financial statements depends on the accounting framework a company follows. Under International Financial Reporting Standards, IAS 38 sets out the criteria for recognizing intangible assets. It explains that internally generated brands are generally not recognized as intangible assets, and that expenditure on advertising and promotional activities is generally recognized as an expense when incurred.3 Companies reporting under other frameworks, such as UK GAAP, may apply different rules, so accounting advice specific to the situation is typically needed.
In practice, this means many rebranding costs are expensed in the period they occur, which can affect reported profit in that year. Costs for items such as legal registration fees may be treated differently from creative and launch spending, so the classification of each expense is usually reviewed with an accountant.
- Costs generally expensed as incurred: advertising, launch campaigns, and staff training.
- Costs that may need separate assessment: registration fees and certain externally acquired intangible assets.
- Costs whose treatment depends on the framework and facts: system upgrades and digital assets.
Planning and Executing a Rebrand
A rebrand is generally more manageable when it is planned in stages. Many companies begin with a clear statement of the business problem the rebrand is meant to solve, then set measurable objectives before any design work begins. This helps prevent the project from being driven by preferences alone.
- Define the objective: Identify the specific business problem, such as entering a new market or simplifying a multi-brand portfolio.
- Audit current assets: Inventory names, logos, domains, trademarks, and customer touchpoints.
- Test the options: Compare naming and design concepts with target customers and internal stakeholders.
- Build a budget and timeline: Account for legal, physical, digital, and communication costs.
- Plan the transition: Decide whether to launch all at once or phase changes across markets and channels.
- Communicate internally first: Employees are often the most important audience during launch.
Measuring the Results of a Rebrand
Evaluating a rebrand works best when the measures are chosen before launch. Useful indicators often include brand awareness surveys, website traffic, search visibility, customer retention, average transaction value, and sales in the segments the rebrand was designed to reach. Because many factors influence these figures at the same time, companies typically compare results against a baseline period and consider other market conditions before attributing changes to the rebrand itself.
Results may take months or longer to become clear, and the timing varies by industry and customer buying cycle. Management teams commonly set review points at several intervals after launch rather than relying on a single measure.
Key Takeaways for Evaluating a Rebrand
A rebrand is a business decision with financial consequences that extend well beyond design. The following points summarize the main considerations:
- Rebrands are usually driven by market, structural, or reputational factors, and the reason should be clearly defined.
- Brand equity can be affected by a change, so preserving familiar elements may support continuity.
- Costs span strategy, design, legal, physical, digital, and communication categories.
- Accounting treatment depends on the reporting framework and on the nature of each expense.
- Clear objectives and measurable indicators make it easier to judge whether the rebrand delivered its intended results.
Anyone evaluating a rebrand, whether inside a company or as an outside observer, can use these questions as a starting point: What problem is the change solving? What will it cost in total? How will the results be measured, and over what period?